2026 Health Insurance: PPO vs. HMO for Families Analysis
Advertisements
The latest data on 2026 Health Insurance Benefits offers crucial insights for families navigating PPO and HMO options. This analysis provides a factual, up-to-date comparison, highlighting key differences in coverage, costs, and access to care. Readers will gain a clear understanding of what these changes mean for their healthcare decisions now.
Comparing 2026 Health Insurance Benefits: A Data-Backed Analysis of PPO vs. HMO Plans for Families (COMPARISON/ANALYSIS) is a critical task for millions of American households. As open enrollment approaches, understanding the nuances between these prevalent plan types becomes paramount. This report delves into the specifics, offering a clear, objective look at what families can expect.
Our objective is to provide a comprehensive, data-backed perspective on the evolving landscape of 2026 health insurance benefits. We will examine the core structures of PPO and HMO plans, their implications for family healthcare, and the financial considerations involved. The goal is to empower readers with the knowledge needed to make informed choices for their loved ones.
Understanding the Core Differences: PPO vs. HMO Structures
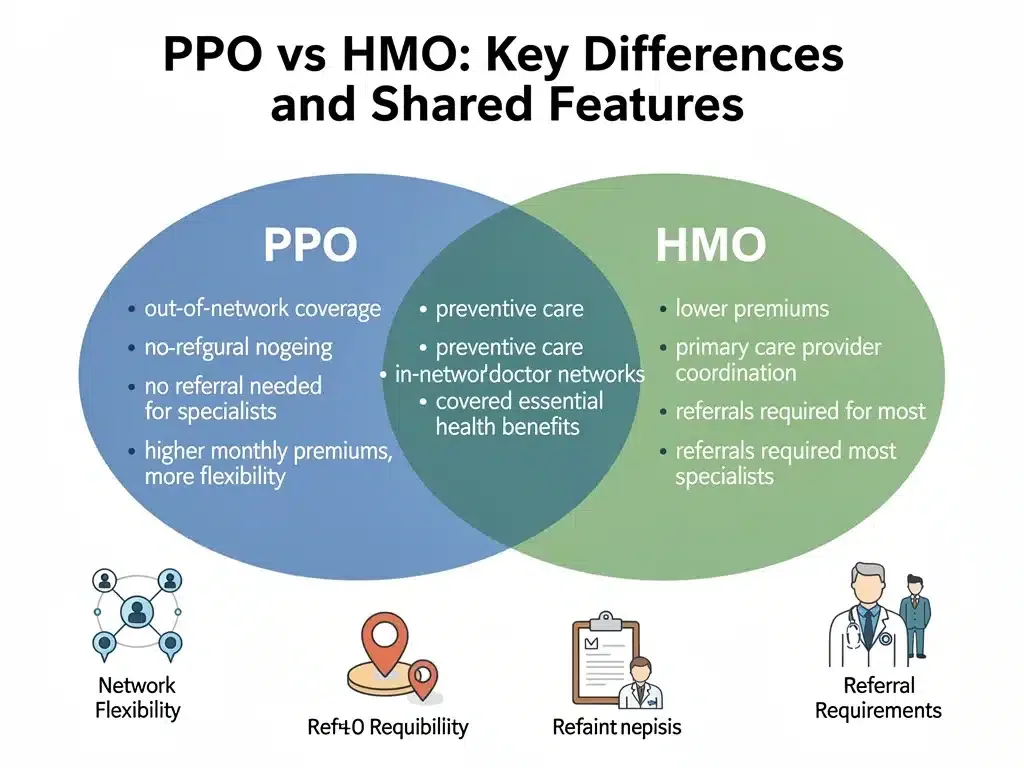
The fundamental distinction between PPO (Preferred Provider Organization) and HMO (Health Maintenance Organization) plans lies in their network structures and how they manage access to care. These differences directly impact a family’s flexibility and potential out-of-pocket expenses for 2026 health insurance benefits.
PPO plans generally offer more flexibility in choosing healthcare providers, allowing members to see out-of-network specialists without a referral. In contrast, HMO plans typically require members to select a primary care physician (PCP) within the network, who then coordinates all care and provides referrals to specialists.
This structural variance is a key factor when families are comparing 2026 health insurance benefits. It dictates not only where care can be sought but also the processes involved in obtaining that care, influencing convenience and accessibility for family members.
Network Flexibility and Provider Choice
PPO plans are renowned for their broader network flexibility, enabling members to seek care from a wider array of doctors and hospitals. While in-network services are generally cheaper, PPOs still cover a portion of out-of-network care, albeit at a higher cost to the patient.
HMOs, on the other hand, operate within a more restricted network of providers, emphasizing integrated care within that system. Choosing an HMO means committing to seeing doctors and specialists within their network, with very few exceptions for out-of-network emergencies.
- PPO: Offers greater freedom to choose doctors and specialists, both in and out of network.
- HMO: Requires selecting a primary care physician (PCP) within the plan’s network.
- PPO: Out-of-network care is covered, but at a higher cost to the member.
- HMO: Generally does not cover out-of-network care, except in emergencies.
This distinction is often the deciding factor for families prioritizing either freedom of choice or a more coordinated, cost-controlled approach to their 2026 health insurance benefits. The impact on specialist access is particularly noteworthy for families with specific healthcare needs.
Cost Implications for Families: Premiums, Deductibles, and Co-pays
When evaluating 2026 health insurance benefits, the financial aspect is often the most significant for families. Premiums, deductibles, co-pays, and out-of-pocket maximums vary considerably between PPO and HMO plans, directly influencing a family’s annual healthcare budget.
Generally, HMO plans tend to have lower monthly premiums compared to PPO plans, making them an attractive option for families seeking to reduce upfront costs. However, this often comes with trade-offs in terms of provider choice and referral requirements, which we discussed previously.
PPO plans, while typically featuring higher premiums, can offer more predictable costs for out-of-network care and often have lower co-pays for certain services once the deductible is met. This balance between premium cost and flexibility is crucial for families assessing their 2026 health insurance benefits.
Deductibles and Out-of-Pocket Maximums
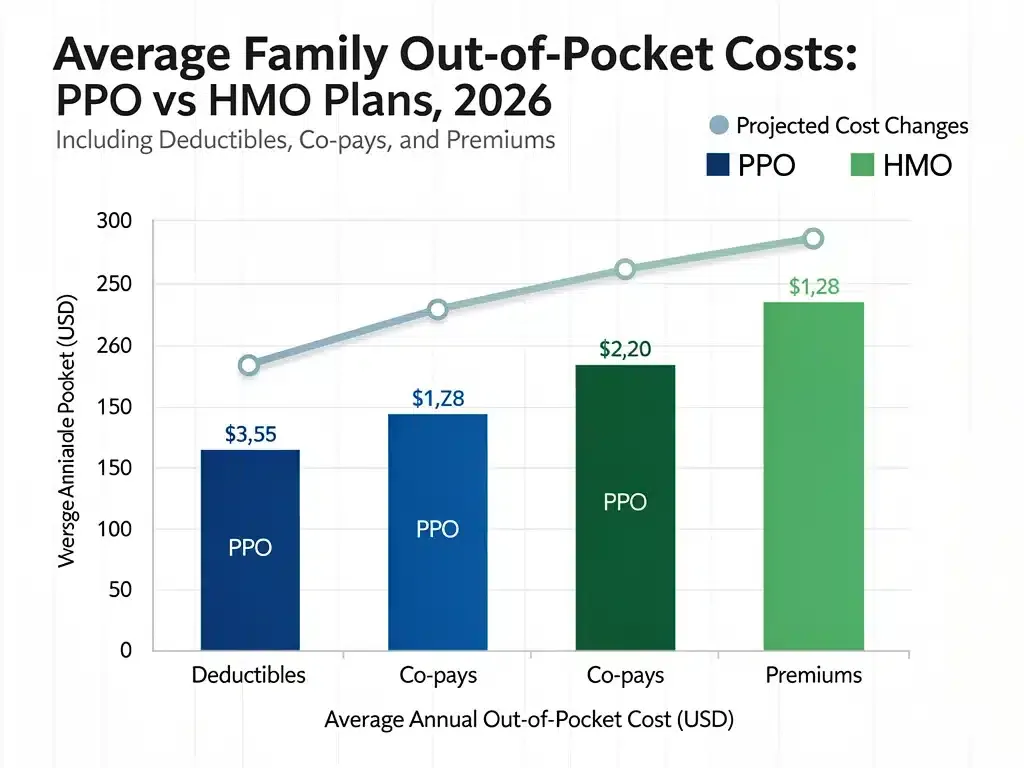
Deductibles, the amount a family must pay before their insurance plan starts to cover costs, can differ significantly. PPO plans often have higher deductibles, meaning families pay more out-of-pocket before their benefits fully kick in, especially for out-of-network services.
HMO plans frequently feature lower or even no deductibles for in-network services, making routine care more accessible from a cost perspective. However, their out-of-pocket maximums, the most a family will pay in a year, are also a critical consideration when comparing 2026 health insurance benefits.
Understanding these thresholds is essential for families, particularly those with chronic conditions or anticipated medical needs. A lower deductible might be appealing, but a higher out-of-pocket maximum could expose a family to significant costs in a catastrophic health event. This is why a thorough examination of 2026 health insurance benefits is so vital.
Referral Systems and Access to Specialists
The mechanism for accessing specialist care is another major differentiator when comparing PPO and HMO plans. This aspect can profoundly impact families, especially those with children who may require specialized medical attention.
HMO plans typically mandate a referral from a primary care physician (PCP) before a member can see a specialist. This gatekeeper system ensures coordinated care but can sometimes delay access to specialized services, as families must first schedule an appointment with their PCP.
PPO plans generally do not require a referral to see a specialist, allowing members to schedule appointments directly. This direct access can be a significant advantage for families who value speed and autonomy in their healthcare decisions, a key consideration for 2026 health insurance benefits.
Impact on Family Healthcare Coordination
For families, the referral system can either streamline or complicate healthcare coordination. An HMO’s PCP-centric approach ensures a single point of contact for all medical needs, fostering a holistic view of a family member’s health history.
While this can be beneficial for preventive care and managing chronic conditions, it also means an extra step for every specialist visit. PPO plans offer more freedom, but families must take on more responsibility for coordinating their own care across different providers, a factor in choosing 2026 health insurance benefits.
- HMO: Requires a PCP referral for specialist visits, promoting coordinated care.
- PPO: No referral typically needed, offering direct access to specialists.
- HMO: Can lead to delays in seeing specialists due to the referral process.
- PPO: Offers greater autonomy in scheduling specialist appointments.
Families with complex health needs or those who frequently visit specialists might find the direct access of a PPO more appealing. Conversely, families who prefer a single point of contact and coordinated care might lean towards an HMO as they compare 2026 health insurance benefits.
Preventive Care and Wellness Programs
Both PPO and HMO plans emphasize preventive care, recognizing its importance in maintaining long-term health and reducing overall healthcare costs. However, the specific wellness programs and incentives offered can differ, influencing a family’s engagement with their health.
HMOs, with their integrated care models, often have robust preventive care programs and may offer incentives for healthy behaviors. Their focus on population health management means they actively encourage regular check-ups, screenings, and wellness activities.
PPO plans also cover preventive services as mandated by the Affordable Care Act, typically without co-pays or deductibles. While they may offer wellness programs, the emphasis might be less on integrated population health and more on individual choice, a nuanced difference for 2026 health insurance benefits.
The Role of Preventive Services in Family Health
Preventive care, such as immunizations, annual physicals, and health screenings, is crucial for families to detect potential health issues early. Both plan types ensure coverage for these essential services, aiming to keep families healthy and reduce the need for more intensive interventions.
For families with young children, consistent access to well-child visits and vaccinations is non-negotiable. Both PPO and HMO plans provide this, but the ease of scheduling and the network of pediatricians can be a distinguishing factor when selecting 2026 health insurance benefits.
The long-term benefits of preventive care cannot be overstated, contributing to healthier family outcomes and potentially lower healthcare expenditures over time. When evaluating 2026 health insurance benefits, families should inquire about specific preventive care offerings and wellness incentives.
Emergency Care and Urgent Care Coverage
Understanding how PPO and HMO plans handle emergency and urgent care is vital, especially for families with active children or unpredictable health needs. These situations often arise unexpectedly, and knowing the coverage details can alleviate significant stress.
Both PPO and HMO plans are legally required to cover emergency services, regardless of whether the facility is in-network or out-of-network. However, the cost-sharing structure, such as co-pays and deductibles, can still vary significantly once the emergency is resolved and follow-up care is needed.
For urgent care, which addresses non-life-threatening but immediate medical needs, the distinction between PPO and HMO becomes more pronounced. HMOs typically require urgent care to be sought within their network or at designated urgent care centers to ensure full coverage.
Navigating Unexpected Medical Needs
PPO plans often offer more flexibility for urgent care, allowing members to visit a broader range of urgent care centers, both in and out of network, though out-of-network costs will be higher. This flexibility can be a comfort to families traveling or residing in areas with limited in-network urgent care options when considering their 2026 health insurance benefits.
Families with an HMO plan should be aware of their plan’s specific urgent care protocols and designated facilities to avoid unexpected costs. Understanding these rules before an urgent situation arises is crucial for maximizing 2026 health insurance benefits.
The distinction between an emergency and urgent care is also important, as insurance companies define these differently, impacting coverage. Families should familiarize themselves with these definitions in their specific 2026 health insurance benefits plan documents.
Prescription Drug Coverage and Formularies
Prescription drug coverage is a critical component of 2026 health insurance benefits, especially for families managing chronic conditions or those with regular medication needs. Both PPO and HMO plans include prescription benefits, but their formularies and cost-sharing can differ.
A formulary is a list of prescription drugs covered by an insurance plan. HMOs often have more restrictive formularies, encouraging the use of generic drugs or preferred brand-name medications. This can lead to lower out-of-pocket costs for common prescriptions but may require prior authorization for non-formulary drugs.
PPO plans typically offer broader formularies, providing more options for brand-name drugs, though often at a higher co-pay or co-insurance. The flexibility to choose a wider range of medications can be a significant advantage for families with complex or specialized prescription needs when reviewing 2026 health insurance benefits.
Managing Medication Costs for Families
For families, understanding the formulary and tier system of their chosen plan is essential for predicting prescription costs. Most plans categorize drugs into tiers, with generic drugs usually in the lowest tier (lowest cost) and specialty drugs in the highest (highest cost).
Comparing 2026 health insurance benefits means carefully examining the prescription drug coverage, particularly if a family member relies on specific medications. It’s advisable to check if current prescriptions are covered and at what cost-sharing level under both PPO and HMO options.
- HMO: Often has more restrictive formularies, favoring generics and preferred brands.
- PPO: Generally offers broader formularies with more brand-name drug options.
- HMO: May require prior authorization for non-formulary medications.
- PPO: Can have higher co-pays or co-insurance for brand-name drugs.
Some plans also offer mail-order pharmacy services, which can provide cost savings and convenience for maintenance medications. Families should explore these options when evaluating their 2026 health insurance benefits to optimize their drug costs.
Data-Backed Insights: Enrollment Trends and Member Satisfaction
Recent data indicates evolving trends in enrollment patterns for PPO and HMO plans, reflecting shifts in consumer preferences and market dynamics. Analyzing these trends provides valuable insights for families considering their 2026 health insurance benefits.
Studies show a continued preference for PPO plans among individuals and families seeking greater flexibility, despite often higher premiums. However, HMO enrollment remains strong, particularly in regions where integrated health systems are prevalent and cost savings are a priority.
Member satisfaction surveys reveal varying levels of contentment with both plan types, largely dependent on individual expectations regarding cost, access, and administrative ease. These insights are crucial for a holistic understanding of 2026 health insurance benefits.
What the Data Tells Us About Family Choices
Data from the Centers for Medicare & Medicaid Services (CMS) and various private health insurance reports highlight that families often choose PPO plans when they prioritize the freedom to select their own doctors and specialists without referrals. This is especially true for those who have established relationships with specific providers.
Conversely, families opting for HMOs frequently cite lower out-of-pocket costs and the coordinated care model as primary motivators. The predictability of expenses and the guidance from a PCP are significant draws for these households when comparing 2026 health insurance benefits.
These trends underscore that there is no one-size-fits-all solution; the ideal plan depends on a family’s unique health needs, financial situation, and preferences for healthcare management. Analyzing this data helps families make more informed choices about their 2026 health insurance benefits.
Making the Right Choice for Your Family’s 2026 Health Insurance Benefits
The decision between a PPO and an HMO plan for 2026 health insurance benefits is highly personal and should be based on a thorough assessment of a family’s specific circumstances. There are several key factors to weigh before committing to a plan.
Consider your family’s current health status, anticipated medical needs, and financial flexibility. Do you have established relationships with doctors who might be out-of-network for an HMO? Do any family members have chronic conditions requiring frequent specialist visits?
Also, evaluate your comfort level with managing referrals versus having direct access to specialists. These considerations are fundamental to selecting the most suitable 2026 health insurance benefits plan for your household.
Key Questions to Guide Your Decision
When comparing 2026 health insurance benefits, ask yourself: What is my budget for monthly premiums and potential out-of-pocket costs? How important is it to have the freedom to choose any doctor or specialist, even if they are out of network?
Do I prefer a coordinated care approach where a primary care physician manages all referrals, or do I want the autonomy to seek specialist care directly? These questions will help clarify which plan type aligns best with your family’s healthcare philosophy and needs.
Ultimately, the best 2026 health insurance benefits plan is one that balances cost, coverage, and access to care, providing peace of mind for your family’s health and financial well-being. Careful research and consideration are key to making an optimal choice.
| Key Feature | PPO vs. HMO Comparison |
|---|---|
| Network Flexibility | PPO offers broad network with out-of-network options; HMO restricts to in-network providers. |
| Referral Requirement | PPO typically no referral needed; HMO requires PCP referral for specialists. |
| Cost Structure | PPO usually higher premiums/deductibles; HMO often lower premiums/deductibles. |
| Emergency Coverage | Both cover emergencies regardless of network; cost-sharing varies post-stabilization. |
Frequently Asked Questions About 2026 Health Insurance Benefits
What are the main advantages of a PPO plan for families?▼PPO plans offer greater flexibility in choosing doctors and specialists, both in and out of network, without requiring referrals. This is beneficial for families who prioritize direct access to specific providers or travel frequently, enhancing their 2026 health insurance benefits experience.
Why might an HMO plan be a better choice for some families?▼HMO plans often come with lower monthly premiums and out-of-pocket costs, making them more affordable for budget-conscious families. The coordinated care approach through a primary care physician can also simplify healthcare management for 2026 health insurance benefits.
How do deductibles differ between PPO and HMO plans for 2026?▼PPO plans typically have higher deductibles, meaning families pay more out-of-pocket before insurance coverage fully kicks in. HMOs often feature lower deductibles or even none for in-network services, impacting upfront costs for 2026 health insurance benefits.
Is prescription drug coverage the same across both plan types?▼While both cover prescriptions, formularies (covered drug lists) can differ. HMOs often have more restrictive formularies, favoring generics, while PPOs offer broader options but potentially higher co-pays for brand-name drugs as part of their 2026 health insurance benefits.
What should families consider when choosing between PPO and HMO?▼Families should assess their budget, preferred doctors, need for specialist access, and comfort with referral systems. Their health needs and travel habits also play a crucial role in deciding between PPO and HMO for 2026 health insurance benefits.
What this means
The analysis of 2026 health insurance benefits for PPO versus HMO plans underscores the importance of personalized decision-making for families. Understanding the nuances of network flexibility, cost structures, and access to specialists is paramount. As healthcare landscapes continue to evolve, staying informed about these critical distinctions will empower families to secure the most appropriate and effective coverage for their needs, ensuring peace of mind and financial stability. Keep an eye on insurer updates and open enrollment resources to finalize your choice.