Capital Gains Tax 2026: Investor Guide to New Rules & Penalties
Advertisements
Latest developments on Recent Changes to Capital Gains Tax in 2026: What Every Investor Needs to Know to Avoid Penalties, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
Recent Changes to Capital Gains Tax in 2026: What Every Investor Needs to Know to Avoid Penalties is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
Authorities confirmed new timelines and outlined initial impacts across different regions. Statements from representatives indicate short-term adjustments and a more defined path for upcoming decisions.
Understanding the Core Changes to Capital Gains Tax in 2026
The landscape of investment taxation is undergoing significant modifications, particularly concerning Capital Gains Tax 2026. These changes, set to take effect in the coming year, necessitate a proactive approach from all investors.
The proposed adjustments aim to address various economic objectives, including revenue generation and wealth redistribution. Investors must grasp the nuances of these reforms to effectively manage their portfolios and comply with new legal requirements.
Failure to understand and adapt to these impending regulations could lead to substantial financial repercussions. Therefore, a comprehensive overview of the core changes is paramount for informed decision-making.
Key Legislative Proposals and Their Impact
Several legislative proposals form the bedrock of the Capital Gains Tax 2026 overhaul. These include potential alterations to the tax rates, holding periods for assets, and exemptions that previously applied to certain investment types.
Initial reports suggest a potential increase in the top marginal capital gains tax rate, aligning it more closely with ordinary income tax rates for high-income earners. This shift could fundamentally change the after-tax returns on long-term investments.
Furthermore, there are discussions around modifying the definition of what constitutes a long-term capital gain, potentially extending the required holding period for preferential tax treatment. Such changes would require investors to reconsider their investment horizons.
- Potential increase in top capital gains tax rates.
- Adjustments to long-term capital gain holding periods.
- Review of existing capital gains tax exemptions.
Who Will Be Most Affected by the Capital Gains Tax 2026 Reforms?
While the Capital Gains Tax 2026 reforms will touch all investors, certain groups are expected to feel the impact more acutely. High-net-worth individuals and those with significant unrealized gains in their portfolios are particularly vulnerable.
Investors engaged in frequent trading or those with substantial portfolios of appreciated assets will need to pay close attention. The changes could significantly alter their tax liabilities and influence their investment strategies.
Additionally, owners of small businesses and real estate investors might also face new challenges. The disposition of business assets or investment properties could trigger higher tax burdens under the revised regulations.
High-Net-Worth Individuals and Active Traders
For high-net-worth individuals, the potential alignment of capital gains rates with ordinary income rates could result in a substantial increase in their tax obligations. This is especially true for those whose annual income places them in the highest tax brackets.
Active traders, who frequently realize short-term capital gains, may also see their tax burden rise if the distinction between short-term and long-term gains is blurred or if short-term rates are also adjusted upwards. Their trading profitability could be directly impacted.
These groups will need to engage in sophisticated tax planning strategies to mitigate the effects of the new rules. Proactive engagement with financial advisors will be essential to navigate this complex environment effectively.
Strategies to Mitigate Impact and Avoid Penalties
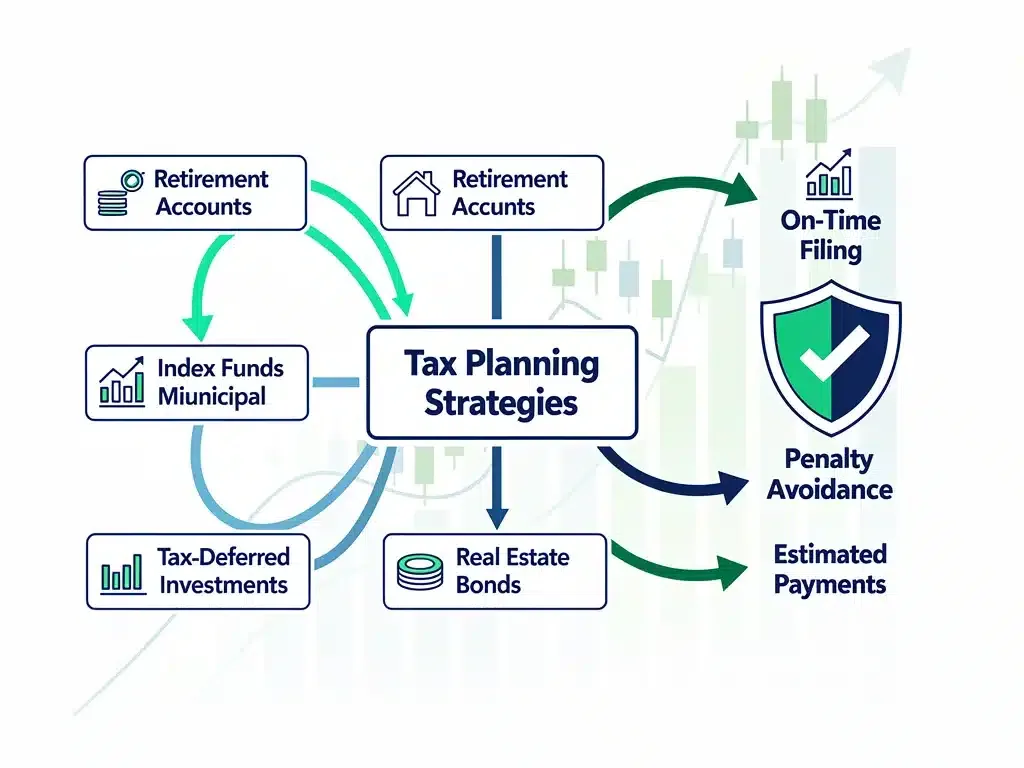
Navigating the Capital Gains Tax 2026 changes effectively requires strategic planning and timely action. Investors have several avenues to explore to mitigate potential impacts and, crucially, avoid costly penalties.
One primary strategy involves accelerating the realization of gains before the new rules take effect, if financially prudent. This could allow investors to lock in current, potentially lower, tax rates on their appreciated assets.
Another critical approach is to re-evaluate portfolio allocation and consider tax-loss harvesting opportunities. These strategies can help offset gains and reduce overall tax liability under the new regime.
Pre-Emptive Measures and Portfolio Adjustments
Investors should consider conducting a thorough review of their current portfolios with a tax professional. This review can identify assets with significant unrealized gains that might be subject to higher taxes under the new Capital Gains Tax 2026 rules.
For some, it might be beneficial to realize gains on certain assets before January 1, 2026, to benefit from current tax rates. This decision, however, should be made carefully, considering individual financial goals and market conditions.
Adjusting asset allocation to include more tax-efficient investments or exploring strategies like qualified opportunity zones could also be viable options. These measures require careful planning and understanding of their specific requirements.
- Accelerate gain realization before 2026.
- Re-evaluate current portfolio for tax efficiency.
- Explore tax-loss harvesting opportunities.
The Role of Tax-Loss Harvesting Under New Regulations
Tax-loss harvesting, a strategy where investors sell investments at a loss to offset capital gains, will remain a vital tool under the Capital Gains Tax 2026 framework. Its importance may even increase as tax rates potentially rise.
This strategy allows investors to reduce their taxable income by offsetting capital gains with capital losses. Any excess losses can typically be used to offset a limited amount of ordinary income and carried forward to future tax years.
Understanding the rules surrounding wash sales and the proper timing of these transactions is crucial to effectively utilize tax-loss harvesting. Incorrect application can invalidate the tax benefit.
Maximizing Deductions and Offsets
As the tax landscape shifts with Capital Gains Tax 2026, maximizing all available deductions and offsets becomes even more critical. Beyond tax-loss harvesting, investors should explore other avenues to reduce their taxable income.
This includes contributing to tax-advantaged retirement accounts like 401(k)s and IRAs, which can defer or reduce tax liabilities. Charitable contributions of appreciated securities can also offer significant tax benefits.
Consulting with a financial advisor is essential to identify all applicable deductions and ensure compliance with the new regulations. A tailored approach can significantly enhance an investor’s after-tax returns.
Impact on Retirement Planning and Long-Term Investments
The Capital Gains Tax 2026 changes are poised to have a substantial impact on retirement planning and long-term investment strategies. Investors nearing retirement or those with extended investment horizons must recalibrate their financial plans.
Higher capital gains taxes could reduce the net accumulation of wealth over time, necessitating adjustments to savings rates or investment choices. The long-term compounding effect could be diminished.
Consideration should be given to the tax implications of withdrawing from various retirement accounts. Understanding how different account types are taxed upon distribution becomes even more important.
Adjusting Retirement Account Strategies
For many, retirement accounts like 401(k)s and IRAs offer tax-deferred or tax-free growth, shielding capital gains from annual taxation. However, the ultimate tax treatment upon withdrawal still needs careful consideration in light of Capital Gains Tax 2026.
Reviewing whether to contribute to traditional or Roth accounts might become more critical. Roth accounts, offering tax-free withdrawals in retirement, could become even more attractive if capital gains rates significantly increase.
Long-term investors should also evaluate the tax efficiency of their investment vehicles. Exchange-Traded Funds (ETFs) and certain mutual funds are often more tax-efficient than actively managed funds due to their structure and lower turnover.
Potential Penalties for Non-Compliance with Capital Gains Tax 2026
Understanding the new rules is not merely about optimizing returns; it is fundamentally about avoiding severe penalties associated with non-compliance. The IRS is expected to rigorously enforce the Capital Gains Tax 2026 regulations.
Penalties for underpayment of taxes, late filing, or inaccurate reporting can include significant fines and interest charges. In some cases, severe non-compliance could lead to criminal charges.
It is paramount for investors to maintain meticulous records of all investment transactions, including purchase dates, sale dates, and cost bases. Accurate record-keeping is the first line of defense against potential audits and penalties.
Ensuring Accurate Reporting and Timely Filing
Accurate reporting of capital gains and losses is non-negotiable under the new Capital Gains Tax 2026 regime. Investors must ensure that all relevant forms, such as Schedule D (Form 1040), are completed correctly and filed on time.
Utilizing reliable tax software or engaging a qualified tax professional can significantly reduce the risk of errors. These resources can help navigate the complexities of the new tax laws and ensure all deductions and credits are properly claimed.
Furthermore, making estimated tax payments throughout the year, especially if significant capital gains are anticipated, can help avoid underpayment penalties. Staying informed and proactive is key to compliance.
Expert Insights and Professional Guidance for Capital Gains Tax 2026
Given the complexity and potential impact of the Capital Gains Tax 2026 changes, seeking expert insights and professional guidance is more critical than ever. Tax laws are intricate, and a nuanced understanding is required.
Financial advisors, tax attorneys, and certified public accountants (CPAs) specialize in these areas and can provide tailored advice. Their expertise can help investors understand the specific implications for their unique financial situations.
Engaging with these professionals early can facilitate proactive planning, allowing investors to adapt their strategies before the new rules fully take effect. This foresight can lead to substantial savings and peace of mind.
Choosing the Right Financial and Tax Advisor
Selecting a financial or tax advisor with a deep understanding of current and impending tax laws, particularly those related to Capital Gains Tax 2026, is crucial. Look for professionals with a strong track record and relevant certifications.
A good advisor will not only explain the new regulations but also help develop a personalized tax strategy that aligns with your financial goals and risk tolerance. They can identify opportunities for tax minimization that you might overlook.
Regular communication with your chosen advisor is also vital. The tax landscape can evolve, and ongoing guidance ensures your strategies remain effective and compliant with the latest regulatory updates.
| Key Aspect | Brief Description |
|---|---|
| Tax Rate Changes | Potential increase in capital gains rates, especially for high earners. |
| Holding Period Adjustments | Possible extension of long-term capital gain holding requirements. |
| Penalty Avoidance | Strategic planning and accurate reporting are crucial to avoid fines. |
| Expert Consultation | Engaging tax professionals is vital for personalized guidance and compliance. |
Frequently Asked Questions About Capital Gains Tax in 2026
What are the primary changes expected for Capital Gains Tax in 2026?▼The primary changes anticipated for Capital Gains Tax 2026 include potential increases in tax rates, especially for high-income individuals, and adjustments to the holding periods required for assets to qualify as long-term gains. These modifications aim to generate more revenue and ensure greater equity in the tax system.
How can investors avoid penalties under the new Capital Gains Tax 2026 rules?▼To avoid penalties related to Capital Gains Tax 2026, investors should prioritize accurate record-keeping, ensure timely and correct filing of tax forms, and consider making estimated tax payments. Consulting with a qualified tax professional is also highly recommended to navigate complexities and ensure full compliance.
Will these changes affect long-term investment strategies?▼Yes, the changes to Capital Gains Tax 2026 are likely to significantly impact long-term investment strategies. Investors may need to re-evaluate their portfolio allocations, consider tax-efficient investment vehicles, and adjust their retirement planning to account for potentially higher tax liabilities on appreciated assets.
What role does tax-loss harvesting play in the new tax environment?▼Tax-loss harvesting will continue to be a crucial strategy under the new Capital Gains Tax 2026 rules. It allows investors to offset capital gains with capital losses, thereby reducing their overall taxable income. Proper implementation, avoiding wash sales, is essential for maximizing its benefits.
When should investors start preparing for Capital Gains Tax 2026?▼Investors should start preparing for Capital Gains Tax 2026 immediately. Proactive planning, including reviewing current portfolios, consulting with tax professionals, and understanding the proposed legislative changes, will allow for timely adjustments and help mitigate potential adverse impacts before the new regulations take full effect.
What This Means for Investors
The impending Capital Gains Tax 2026 changes underscore the need for vigilance and strategic financial planning. These reforms are not merely bureaucratic adjustments; they represent a fundamental shift in how investment returns will be taxed, with direct implications for wealth accumulation and distribution.
Investors must move beyond passive observation and actively engage with the new tax landscape. This involves educating oneself, seeking professional counsel, and adapting investment strategies to align with the revised regulations. The goal is not just compliance, but also optimizing financial outcomes in a changing environment.
The coming months will be crucial for making informed decisions that will safeguard investments and ensure financial stability under the new tax regime. Staying ahead of these developments is the best defense against potential penalties and missed opportunities.