High-Yield Savings Accounts 2026: 5.0% APY Emergency Fund
Advertisements
Leveraging High-Yield Savings Accounts in 2026: Earning up to 5.0% APY on Your Emergency Fund is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
As the financial landscape evolves, optimizing your savings has never been more crucial, especially for essential funds. The prospect of earning a substantial 5.0% Annual Percentage Yield (APY) on an emergency fund represents a significant opportunity for individuals in the United States.
This article delves into the current state and future projections for high-yield savings accounts, offering practical insights and expert analysis to help you navigate this advantageous financial tool effectively.
Understanding High-Yield Savings Accounts in 2026
High-yield savings accounts (HYSAs) are deposit accounts that typically offer significantly higher interest rates than traditional savings accounts. These accounts are usually offered by online-only banks, which have lower overhead costs and can pass those savings on to their customers in the form of better rates.
For 2026, the financial market anticipates a competitive environment, driven by potential shifts in federal interest rates and increased competition among financial institutions. This environment could push APYs for high-yield savings accounts even higher, making them an indispensable tool for growing your emergency fund.
The primary benefit of a high-yield savings account is its ability to generate more passive income on your deposited funds, ensuring your money works harder for you. This is particularly valuable for emergency funds, which need to be both accessible and capable of retaining their purchasing power against inflation.
The Mechanics of APY and Interest Rates
Annual Percentage Yield (APY) reflects the real rate of return earned on a savings deposit, taking into account the effect of compounding interest. This means that the interest earned also earns interest, leading to faster growth of your principal.
Understanding the difference between APY and interest rate is crucial; while an interest rate is the simple percentage charged on a loan or paid on a deposit, APY provides a more accurate picture of your actual earnings over a year. Banks often use daily compounding, which maximizes the benefit of APY for savers.
- APY includes compounding, offering a true return.
- Interest rates are base percentages, simpler but less comprehensive.
- Daily compounding maximizes earnings in high-yield savings accounts.
- Higher APY means faster growth for your emergency fund.
Distinguishing HYSAs from Traditional Accounts
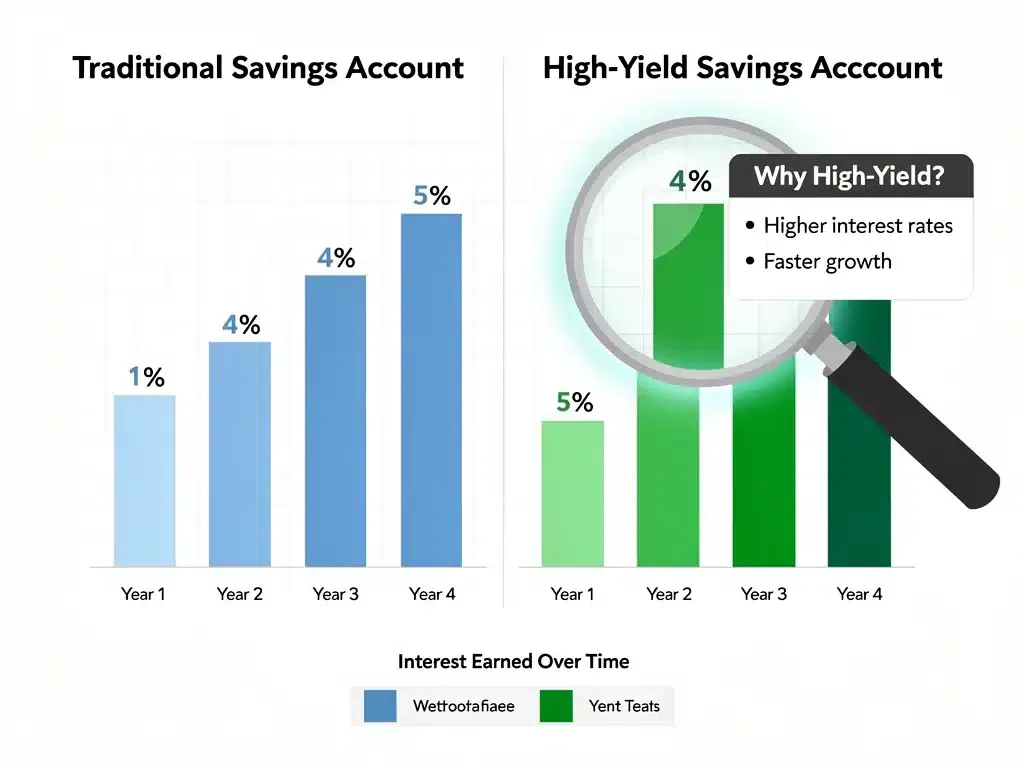
Traditional savings accounts, often found at brick-and-mortar banks, typically offer very low interest rates, sometimes as low as 0.01% APY. This negligible return means your money barely grows, and its value can even erode over time due to inflation.

In contrast, high-yield savings accounts can offer rates many times higher, currently ranging from 3.5% to over 5.0% APY, depending on market conditions and the financial institution. This substantial difference can translate into hundreds or even thousands of dollars in extra earnings over several years, significantly boosting your emergency fund.
The accessibility of funds in HYSAs is generally comparable to traditional accounts, with most offering easy online transfers and ATM access. However, some HYSAs might have limits on the number of monthly withdrawals, a factor to consider when planning for immediate access to your emergency funds.
Optimizing Your Emergency Fund with a 5.0% APY
Achieving a 5.0% APY on your emergency fund in 2026 is an ambitious yet attainable goal, offering substantial benefits for your financial resilience. This rate ensures your savings not only keep pace with inflation but actively grow, providing a stronger safety net against unforeseen expenses.
The strategic placement of your emergency fund in a high-yield savings account with such a competitive APY transforms it from a stagnant pool of money into an active asset. This proactive approach to managing your essential savings can significantly enhance your financial security and peace of mind.
Financial experts consistently recommend maintaining an emergency fund equivalent to three to six months of living expenses. By leveraging high-yield savings accounts, you ensure this critical buffer is not just sitting idle but is actively contributing to your overall financial well-being.
Strategies for Finding Top-Tier HYSAs
To identify the best high-yield savings accounts, it is essential to compare various online banks and financial institutions. Look for banks that consistently offer competitive APYs, have a strong reputation for customer service, and are FDIC-insured to protect your deposits up to $250,000.
Consider factors such as minimum balance requirements, monthly fees, and ease of access to your funds. Some accounts might offer higher rates but come with stricter conditions, so a thorough review is necessary to find an account that aligns with your financial habits and needs.
- Compare APYs from multiple online banks.
- Verify FDIC insurance for deposit protection.
- Check minimum balance requirements and potential fees.
- Assess customer service reputation and accessibility features.
Maximizing Your Earnings: Tips and Tricks
Beyond simply choosing a high-yield savings account, several strategies can help you maximize your earnings. Automating your savings contributions, for instance, ensures consistent growth without requiring constant manual effort, making it easier to build your emergency fund.
Regularly review the APY offered by your chosen institution, as rates can fluctuate based on market conditions. If a competitor offers a significantly higher rate, consider transferring your funds to optimize your returns. Staying informed about market trends is key to actively leveraging high-yield savings accounts.
Avoid unnecessary withdrawals from your emergency fund to let the power of compounding work its magic. Each withdrawal reduces your principal, thereby reducing the amount on which interest is calculated. Discipline in managing your emergency fund is paramount for maximizing its growth.
The Role of Federal Reserve Policy in APY Trends
The Federal Reserve’s monetary policy, particularly its decisions regarding the federal funds rate, plays a pivotal role in shaping the APYs offered on high-yield savings accounts. When the Fed raises its benchmark rate, banks typically follow suit by increasing their own interest rates, including those for savings accounts.
Conversely, a reduction in the federal funds rate usually leads to lower APYs across the board. Understanding this correlation is crucial for anticipating future trends and making informed decisions about where to park your emergency fund. The Fed’s actions directly influence the attractiveness of leveraging high-yield savings accounts.
For 2026, economists are closely watching inflation data and employment figures, which heavily influence the Fed’s decisions. A sustained period of high inflation could prompt the Fed to maintain higher rates, potentially keeping high-yield savings accounts very competitive.
Anticipating Rate Changes for 2026
Forecasting interest rates for 2026 involves analyzing a complex interplay of economic indicators and global financial events. While no one can predict the future with absolute certainty, current projections suggest a period of continued vigilance from the Federal Reserve regarding inflation.
This vigilance could mean that while rates might not climb significantly higher than their current levels, they are unlikely to drop drastically either, maintaining a favorable environment for high-yield savings accounts. Such stability would be beneficial for those aiming for a 5.0% APY on their emergency fund.
Financial analysts advise savers to stay agile and prepared to adjust their strategies. Subscribing to financial news alerts and regularly checking reputable economic forecasts can help you anticipate shifts and react promptly to secure the best rates available.
Impact on Your Emergency Fund
The direct impact of favorable interest rates on your emergency fund is straightforward: more money earned with less effort. A 5.0% APY on a substantial emergency fund can translate into hundreds or even thousands of dollars in passive income each year, significantly increasing your financial security.
This growth helps combat the erosive effects of inflation, ensuring that your emergency savings retain their purchasing power over time. In an economic downturn, having a robust and growing emergency fund becomes even more critical, providing a buffer against job loss or unexpected expenses.
Therefore, actively seeking out and maintaining your emergency fund in a high-yield savings account is not just a smart financial move; it’s a strategic imperative for long-term financial health. The benefits of leveraging high-yield savings accounts extend far beyond mere convenience.
Choosing the Right Provider for Your HYSA
Selecting the appropriate financial institution for your high-yield savings account is a decision that requires careful consideration. Not all banks offer the same rates, features, or customer service, and finding the right fit can significantly impact your savings experience and overall returns.
Focus on institutions that are transparent about their fees, offer intuitive online platforms, and provide robust customer support. The goal is to find a bank that not only offers a competitive APY but also makes managing your emergency fund simple and secure.
Online-only banks often lead the market in terms of high-yield savings rates due to their lower operating costs. However, some traditional banks are also beginning to offer competitive online-only savings options, expanding the choices available to consumers looking to maximize their savings.
Key Factors for Comparison
When comparing high-yield savings providers, several key factors should guide your decision-making process. The Annual Percentage Yield (APY) is, of course, a primary consideration, but it shouldn’t be the only one. Look for consistency in rates; some banks might offer promotional rates that drop after a few months.
FDIC insurance is non-negotiable; ensure your deposits are protected up to the legal limit. Also, investigate any minimum balance requirements to earn the advertised APY, as well as any monthly maintenance fees that could eat into your earnings. Accessibility to your funds, including transfer limits and methods, is another critical aspect.
- Consistently high APY, not just promotional rates.
- FDIC insurance for deposit security.
- No hidden fees or stringent minimum balance requirements.
- Easy access to funds and seamless transfer options.
Reputable Online Banks Offering HYSAs
Several online banks have established themselves as leaders in the high-yield savings space, consistently offering competitive rates and excellent customer service. These institutions often provide a streamlined digital experience, making it easy to open and manage an account from anywhere.
Some prominent examples include Ally Bank, Discover Bank, Marcus by Goldman Sachs, and Capital One 360, among others. These banks are known for their strong financial health and commitment to providing value to their savers. They are excellent choices for individuals focused on leveraging high-yield savings accounts.
Before committing, it’s advisable to read recent customer reviews and conduct a quick search for any outstanding complaints or issues. While a high APY is attractive, a reliable and trustworthy banking partner is equally important for your peace of mind.
Potential Challenges and Considerations
While the benefits of leveraging high-yield savings accounts are clear, it’s important to be aware of potential challenges and considerations. The financial landscape is dynamic, and what appears advantageous today might require adjustment tomorrow. Staying informed and adaptable is key to long-term success.
One primary consideration is the fluctuation of interest rates. While a 5.0% APY might be achievable in 2026, market conditions can change, potentially leading to lower rates. This necessitates periodic review of your account to ensure it remains competitive and continues to meet your financial goals for your emergency fund.
Another factor is the potential for introductory or promotional rates that eventually revert to lower standard rates. Always read the fine print to understand the terms and conditions of any high-yield savings account, ensuring transparency about how long a specific APY is guaranteed.
Interest Rate Volatility and Your Savings
Interest rate volatility is an inherent characteristic of the financial markets, directly impacting the returns on high-yield savings accounts. Economic factors such as inflation, central bank policies, and global events can cause rates to rise or fall, affecting how much your emergency fund grows.
While a 5.0% APY is a strong target, it’s prudent to understand that this rate is not necessarily fixed indefinitely. Banks adjust their APYs in response to market conditions, meaning your earnings could increase or decrease over time. This requires a proactive approach to managing your savings.
To mitigate the impact of rate volatility, consider diversifying your savings across different institutions or types of accounts, though your emergency fund should always prioritize liquidity and safety. Regularly monitoring economic forecasts and financial news can help you anticipate changes and make timely adjustments.
Account Fees and Minimum Balance Requirements
Some high-yield savings accounts, while offering attractive APYs, may come with fees or specific minimum balance requirements. These can erode your earnings if not carefully managed, especially if your emergency fund is still in its early stages of accumulation.
Common fees might include monthly maintenance fees, excessive transaction fees, or fees for specific services. Minimum balance requirements could mean that if your balance drops below a certain threshold, you either earn a lower APY or incur a fee, impacting the effectiveness of leveraging high-yield savings accounts.
Always scrutinize the fee schedule and account terms before opening an account. Opt for banks that offer fee-free accounts with no minimum balance requirements, or those where the minimum is easily maintainable with your current financial situation, to ensure maximum growth for your emergency fund.
The Future of High-Yield Savings in 2026
Looking ahead to 2026, the landscape for high-yield savings accounts appears promising for savers. The continued evolution of digital banking, coupled with a potentially stable interest rate environment, suggests that competitive APYs will remain a significant feature of the financial market.
Technological advancements are also expected to enhance the user experience, offering more intuitive interfaces and integrated financial planning tools. This will make it even easier for individuals to manage their emergency funds and track their growth effectively, further promoting leveraging high-yield savings accounts.
The emphasis on financial literacy and personal savings is growing, driving more consumers to seek out efficient ways to grow their money. High-yield savings accounts are perfectly positioned to meet this demand, providing a secure and lucrative option for essential funds.
Technological Advancements in Digital Banking
Digital banking platforms are continually innovating, introducing features that streamline the savings process and enhance security. In 2026, we can expect to see even more sophisticated tools, such as AI-powered financial insights, personalized savings goals, and advanced fraud protection, integrated into high-yield savings accounts.
These advancements will not only make managing your emergency fund more convenient but also more secure. Instant transfer capabilities and seamless integration with other financial applications will further solidify the position of online high-yield savings accounts as a preferred choice for modern savers.
- AI-powered financial insights for personalized savings.
- Enhanced security features and fraud protection.
- Instant transfers and seamless app integrations.
- Intuitive interfaces for better fund management.
The Long-Term Benefits of a Strong Emergency Fund
Beyond the immediate financial gains, cultivating a robust emergency fund in a high-yield savings account offers profound long-term benefits. It provides an unparalleled sense of financial security, reducing stress and allowing you to face unexpected life events with confidence.
A well-funded emergency account prevents you from incurring high-interest debt, such as credit card balances or personal loans, during crises. This protects your credit score and prevents a domino effect of financial instability, underscoring the importance of leveraging high-yield savings accounts.
Ultimately, a strong emergency fund is a cornerstone of a healthy financial life, enabling you to pursue other financial goals, such as investing for retirement or saving for a down payment, without the constant worry of unforeseen expenses derailing your plans. It is an investment in your future self.
| Key Point | Brief Description |
|---|---|
| 5.0% APY Goal | Target rate for significant emergency fund growth in 2026. |
| HYSA Benefits | Higher returns, inflation protection, and liquidity for emergency funds. |
| Fed Rate Impact | Federal Reserve policy directly influences HYSA APYs. |
| Provider Selection | Compare FDIC insurance, fees, and customer service for optimal choice. |
Frequently Asked Questions About High-Yield Savings Accounts
What is the typical APY for high-yield savings accounts in 2026?▼While rates fluctuate, many high-yield savings accounts are projected to offer APYs between 3.5% and 5.0% in 2026, depending on market conditions and specific bank offerings. It is crucial to compare various institutions to find the most competitive rates for your emergency fund.
Are high-yield savings accounts safe for an emergency fund?▼Yes, high-yield savings accounts are generally very safe, especially if they are FDIC-insured. This insurance protects your deposits up to $250,000 per depositor, per insured bank, in the event of bank failure, making them an ideal choice for your emergency fund.
How do I find the best high-yield savings account?▼To find the best high-yield savings account, compare APYs, check for FDIC insurance, review minimum balance requirements, and scrutinize any potential fees. Reading customer reviews and considering online-only banks often leads to better options for leveraging high-yield savings accounts.
Can I access my money easily from a high-yield savings account?▼Most high-yield savings accounts offer convenient access to your funds through online transfers, mobile banking, and sometimes ATM cards. While some may have limits on monthly withdrawals, they generally provide sufficient liquidity for emergency situations, making them suitable for your emergency fund.
How does the Federal Reserve affect high-yield savings rates?▼The Federal Reserve’s decisions on the federal funds rate directly influence the interest rates banks offer, including those for high-yield savings accounts. When the Fed raises rates, HYSAs typically follow suit, offering higher APYs, and vice-versa, impacting your emergency fund’s growth.
Looking ahead
The current financial outlook for 2026 suggests a sustained period where leveraging high-yield savings accounts will remain a cornerstone of sound personal finance. The pursuit of a 5.0% APY on your emergency fund is not merely aspirational but a tangible goal, supported by ongoing market dynamics and banking competition. Consumers should continue to monitor Federal Reserve announcements and compare offerings from various institutions to ensure their emergency fund is optimally positioned for growth and security. This proactive approach ensures financial resilience in an ever-changing economic environment.